Straightforward advice to build lasting property wealth.

Pal KaurProperty lending & investment consultant, The Smart Advice Collective

Buying your first home, growing a portfolio or working for yourself? Pal finds the lender and loan structure that fit where you are, and explains every step in English, Hindi or Punjabi.

  • Auckland & NZ-wide
  • English, Hindi and Punjabi
  • Your first conversation is free
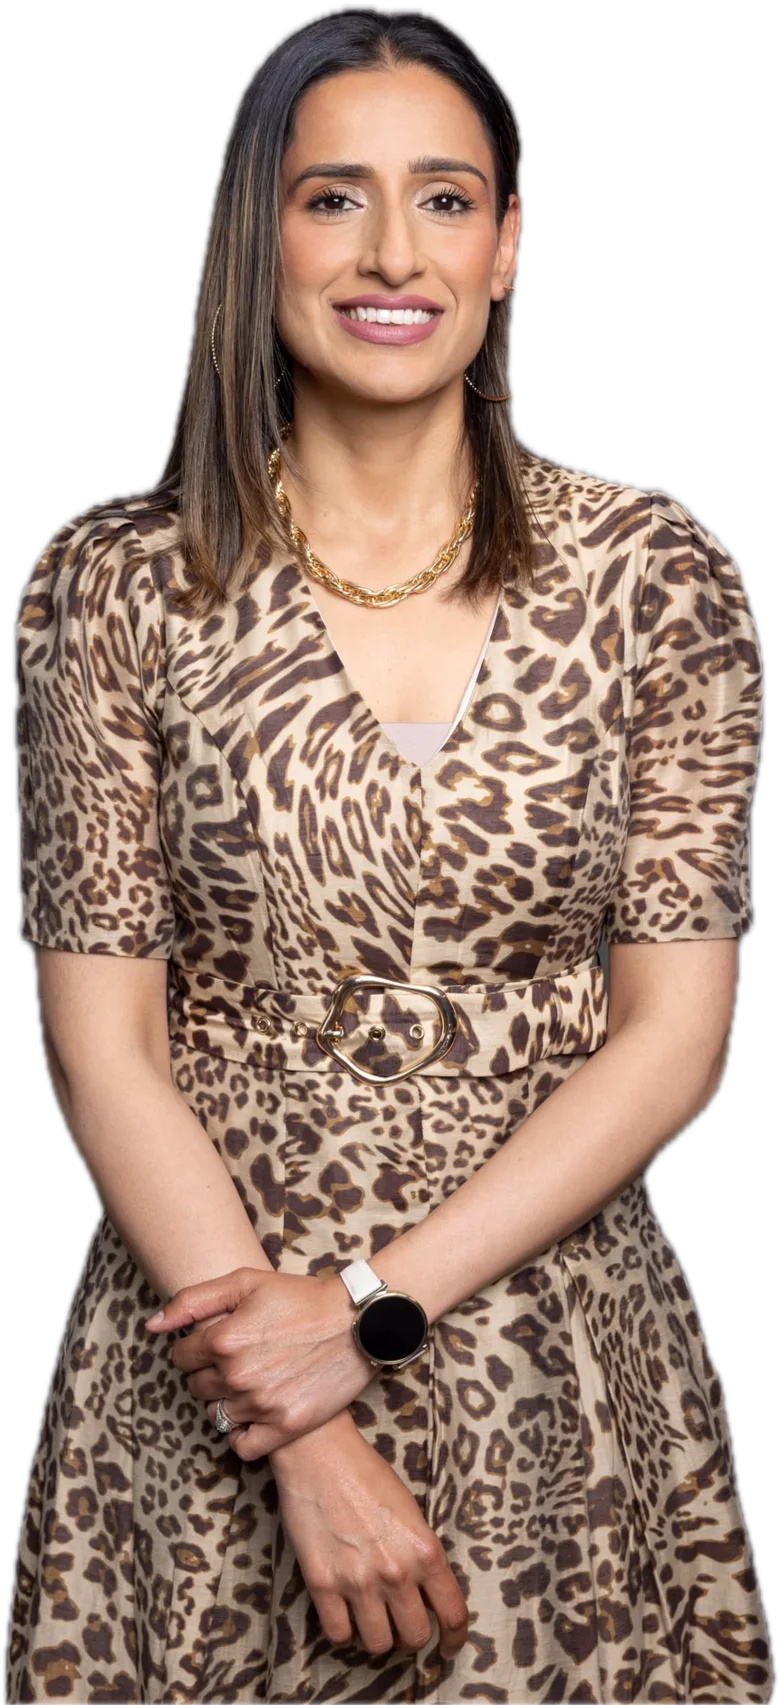
Pal Kaur smiling, wearing a leopard-print dress and gold necklace

Fifteen years on the finance side of the table. Now Pal sits on yours.

Pal Kaur helps everyday New Zealanders borrow with confidence, from first-home buyers and growing families to property investors and people who work for themselves.

Before advising, Pal spent more than 15 years in banking, financial services and corporate administration. That time taught her how lenders assess an application, what slows one down, and how to present your situation so it is understood the first time.

She pairs that with a strong background in community engagement and relationship building. Expect plain answers, no jargon and no pressure. No question is too small.

Qualification
New Zealand Certificate in Financial Services (Level 5), specialising in residential property lending
Focus
Home loans, investment property lending, restructuring and top-ups
Based in
Auckland, helping clients right across New Zealand

Where Pal’s experience comes from

  • Standard Chartered Bank
  • Fonterra
  • KPMG

More than 15 years across banking, financial services and corporate administration.

Talk it through in the language you think in.

A home loan is one of the biggest decisions you will make, and it should be explained in the words that feel most natural to you. Pal advises in English, Hindi and Punjabi, so you and the people who help you decide can follow every detail.

  • Kia oraEnglish
  • नमस्तेHindi
  • ਸਤ ਸ੍ਰੀ ਅਕਾਲPunjabi

Where are you on the property ladder?

Choose the situation closest to yours to see how Pal can help.

Buying your first home

Your first purchase comes with the most unknowns. Pal turns them into a plan: what you can comfortably borrow, how much deposit you really need, and which lenders suit you.

  • Work out a budget you can live with, not just the most a bank will lend
  • Use your KiwiSaver first-home withdrawal toward your deposit
  • Check whether a First Home Loan with a 5% deposit fits your situation
  • Get pre-approval so you can make offers with confidence
  • Keep your lawyer, lender and timeline in step right through to settlement
Building a property portfolio

Growing a portfolio is about structure as much as interest rates. Pal looks at your equity, cash flow and the order you buy in, so each purchase sets up the next one.

  • Review the usable equity in the properties you already own
  • Model your borrowing capacity before you start looking
  • Structure loans to keep flexibility across lenders
  • Plan around investor deposit rules, which differ for new builds

Borrowing when you work for yourself

Lenders read self-employed income differently from a payslip. Pal knows what they look for and helps present your numbers so they are understood the first time.

  • Prepare your financial statements and tax returns the way lenders read them
  • Match you with lenders comfortable with how you earn: sole trader, company or contractor
  • Time your application around your financial year
  • Explain the options if your trading history is still short

Refinancing, restructuring and top-ups

Already have a mortgage? A review can be worth more than a sharper rate. Pal checks your structure, your refix dates and your options for extra lending.

  • Compare your current deal with what other lenders offer for the same loan
  • Balance fixed and floating portions for certainty and flexibility
  • Top up for renovations or major purchases, kept structured and sustainable
  • Plan refixing ahead so you are never rushed when a term ends

From the inside

How lenders decide

Pal spent 15 years on the finance side of the table. These are the six things a lender weighs up when it looks at your home loan application, and what tends to help.

Draft for Pal to review. Written from general New Zealand lending practice, not yet in Pal’s own words. Please check before this page is shared with clients.

  1. Your income

    What they look atHow much you earn, how steady it is and how long you have earned it. Overtime, bonuses and self-employed income are often counted differently from base pay, and Reserve Bank rules limit how much banks can lend to people borrowing many times their income.

    What helpsRecent payslips, or two years of financials if you are self-employed.

  2. Your spending

    What they look atYour bank statements, usually the last three months. Lenders check that the new repayments fit around what you actually spend, not an estimate.

    What helpsA few steady months before you apply, with fewer overdrawn days and fewer subscriptions you do not use.

  3. Your debts and limits

    What they look atCredit cards, car loans, buy now pay later and student loans. A card’s full limit can count against you, even if you pay it off every month.

    What helpsLowering or closing card limits you do not need, and clearing small debts where you can.

  4. Your deposit

    What they look atHow much of the price you are putting in yourself. A bigger deposit usually means more lenders and better options, and Reserve Bank rules limit how much banks lend to buyers with small deposits.

    What helpsSavings built up over time, your KiwiSaver for a first home, or a gift from family with a gift letter.

  5. Your credit history

    What they look atYour credit report shows missed payments, defaults and how often you have applied for credit recently.

    What helpsChecking your free credit report before you apply, and holding off on new credit just before a home loan.

  6. The property itself

    What they look atThe home’s type, size, location and condition. Some properties, like very small apartments or homes with weathertightness issues, need a bigger deposit or a specialist lender.

    What helpsTalking to Pal before you make an offer, so you know which lenders suit the property.

Not sure how a lender would see you?Every lender is different. Pal can tell you which ones suit your situation.

Ask Pal, free

General information, not personal advice. Lender policies and Reserve Bank rules change.

From first chat to keys in hand

A clear path, with Pal handling the paperwork and the bank so you can focus on the move.

  1. A free first chat

    Tell Pal what you are planning and where you are at. There is no cost and no obligation, just a clear sense of your next step.

  2. Your borrowing picture

    Pal looks at your income, debts, spending and deposit to work out what you can borrow and what you can comfortably afford. That is about more than the interest rate.

  3. Compare lenders and apply

    Pal compares what different lenders will offer for your situation, recommends a structure, prepares the application and deals with the bank for you.

  4. Approval to settlement

    Lenders can take one to two weeks to assess an application. Pal keeps it moving, explains any conditions and works with your lawyer through to settlement day.

  5. Ongoing reviews

    Pal stays in touch with reviews and refix reminders, so your loan keeps working for you as rates and life change.

What to have ready

0 of 7 ready

Missing a few? Book the chat anyway. Pal will tell you what matters most for your situation.

What does Pal’s advice cost you?

For most home loans, nothing directly.

When your loan settles, the lender pays a commission to The Smart Advice Collective. That is how most mortgage advice in New Zealand is paid for, and it does not add to your loan.

  • Your first conversation is free, with no obligation to continue
  • Any fee for lending outside standard mortgage advice is agreed with you before work starts
  • The Collective never holds your money. Your loan stays in your name with your lender
  • Ask Pal for her disclosure statement at any time. It sets out how she is paid and how to raise a concern

Estimate your repayments

Move the numbers to see roughly what a loan could cost. Then talk to Pal about what is realistic for you.

$650,000
5.00%
30 years
Repayments

Weekly repayment

$805

Amount borrowed
$650,000
Total interest
$605,296
Total repaid
$1,255,296
Check these numbers with Pal

What if you paid a little extra?

$50

4 yrs 1 mthsooner mortgage-free

$93,780less interest

Loan balance over timeStandardWith extra

An estimate for a principal and interest loan at one rate for the whole term. Real rates change over time, lenders calculate slightly differently and some fixed-rate loans limit extra repayments. This is general information, not financial advice.

How much deposit do you need?

The Reserve Bank sets limits on low-deposit lending, and every lender adds its own criteria on top. Here is where most people start.

How close is your deposit?

You’re buying
$750,000
$60,000
$45,000

You usually need to leave $1,000 in your KiwiSaver.

Your deposit

$105,00014%

Loan you’d need
$645,000
A 20% deposit is
$150,000
  • 20%

    A home to live in

    The usual starting point for an existing home. Banks can lend a limited share to buyers with less, so a smaller deposit is sometimes possible.

  • 30%

    An investment property

    The usual starting point for an existing rental. Lending to investors with less is tightly limited.

  • Less

    New builds

    New builds are exempt from the Reserve Bank’s deposit rules, so some lenders will accept less for both homes and investments.

  • 5%

    First Home Loan

    Underwritten by Kāinga Ora and offered through participating lenders for eligible first-home buyers. Income and price caps apply.

Based on Reserve Bank settings as at November 2026. Lenders also look at your total debt compared with your income. Rules change, so Pal will confirm what applies to you.

The Smart Advice Collective logo

Backed by The Smart Advice Collective

“To empower everyday New Zealanders to make confident, informed financial decisions.”

Meet the whole Collective
  • Emerging Business of the Year 2026

    Awarded to The Smart Advice Collective at the 2026 WealthPoint conference.

  • A team of women advisers across New Zealand

    From Whangārei to Christchurch, a deliberately all-female team with decades of combined experience.

  • Everything around your home, in one place

    Once your loan is sorted, Pal’s colleagues can help protect it with home, life and income insurance, and grow your KiwiSaver and investments.

  • Every new client gives back

    The Collective makes a donation to Women’s Refuge NZ for each new client it welcomes.

Questions people ask Pal

Not seeing yours? Pal is happy to answer it, however simple it seems.

Call 021 032 3711
How much can I borrow?

It depends on your income, your existing debts, your living costs and your deposit. Lenders also now look at your total debt compared with your income. Pal can give you a realistic figure after a short conversation, and help you decide what you are comfortable borrowing, which is not always the maximum.

How long does a home loan approval take?

Lenders can take one to two weeks to assess an application, sometimes less. Having your documents ready makes the biggest difference, which is why Pal helps you prepare before anything goes to a bank.

Can I use my KiwiSaver for a deposit?

Usually, yes. If you have been a member for at least three years and are buying your first home to live in, you can generally withdraw most of your balance, leaving $1,000 in the account. Pal can walk you through the timing so the funds are ready when you need them.

I am self-employed. Can I still get a home loan?

Yes. Lenders will want to see your financial statements and tax returns, and some are more comfortable with self-employed income than others. Pal matches you with lenders that suit how you earn.

Is my current mortgage set up the right way?

A quick review can tell you. Pal looks at your plans for the property and your family, then recommends a structure that balances flexibility, cost certainty and spreading your refix dates.

Can I afford an investment property?

Pal reviews the equity in property you already own, your borrowing capacity and the deposit rules for investors, then shows you what is realistic before you start looking.

Am I getting the best deal from my bank?

Pal can compare your current offer with what other lenders would provide for the same loan amount and property value, so you know whether to stay, negotiate or switch.

Do I need to be in Auckland?

No. Pal is based in Auckland and helps clients right across New Zealand.

Can we talk in Hindi or Punjabi?

Absolutely. Pal advises in English, Hindi and Punjabi. Just let her know which you prefer when you get in touch.

Pal Kaur

Book a free first chat with Pal

Tell Pal what you are planning and where you are at. You will leave with a clear next step, whether you are ready to buy now or a year away.

Your advice, protected

Who gives the advice, what to do if something isn’t right, and how your information is looked after.

Who gives the advice

Pal is part of The Smart Advice Collective. Advisers at the Collective provide financial advice on behalf of Wealthpoint Limited (FSP678011), which holds a Financial Advice Provider licence.

Pal’s FSP number: to confirm. Her disclosure statement explains what she advises on, how she is paid and any conflicts of interest. Disclosure link to confirm

Check the Financial Service Providers Register(opens in a new tab)

If something isn’t right

  1. Tell PalCall or email and explain what has gone wrong and what you would like to happen.
  2. Wealthpoint’s complaints processIf it isn’t resolved, Wealthpoint Limited manages complaints about its advisers. Contact details to confirm
  3. An independent dispute resolution schemeStill not sorted? You can take it to an independent scheme. It costs you nothing. Scheme name to confirm

Your privacy

Your details are held securely by your adviser’s business and Wealthpoint Limited, and used to give you advice and look after your products. You can ask to see or correct the information held about you at any time.

Read the privacy policy (opens in a new tab)

To confirm before launch: the name and contact details of Wealthpoint’s dispute resolution scheme; how clients reach Wealthpoint’s complaints team; Pal’s FSP number; a link to Pal’s disclosure statement. SAC’s current adviser disclosure statements don’t include a complaints process or dispute scheme, which the disclosure rules call for.

Call PalEmail