Winner, WealthPoint Emerging Business of the Year 2026

Insurance, mortgages, KiwiSaver and investments, explained in plain English by a team of women advisers who look after you like family. Based in Auckland, helping New Zealanders everywhere.

Meet our advisers, from Whangārei to ChristchurchOnline, by phone or in person, wherever you are
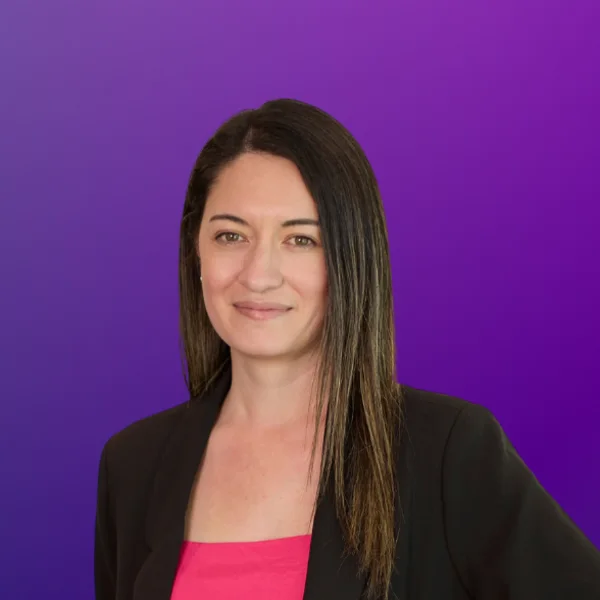
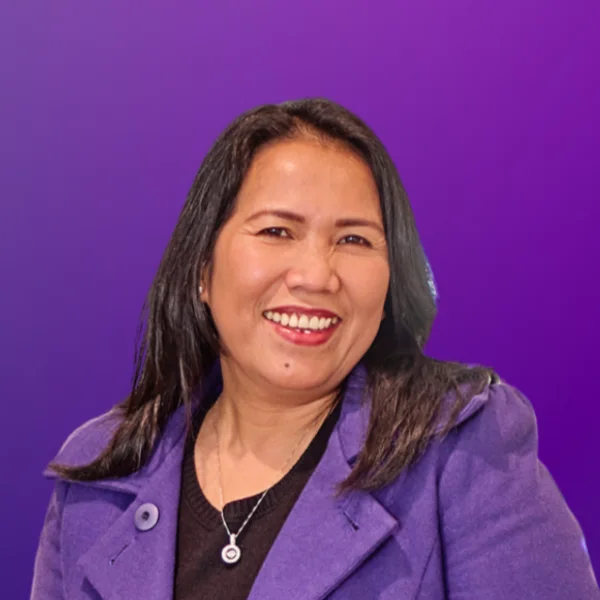
Rachael Thompson, mortgage and KiwiSaver adviser
Rachael Mortgages
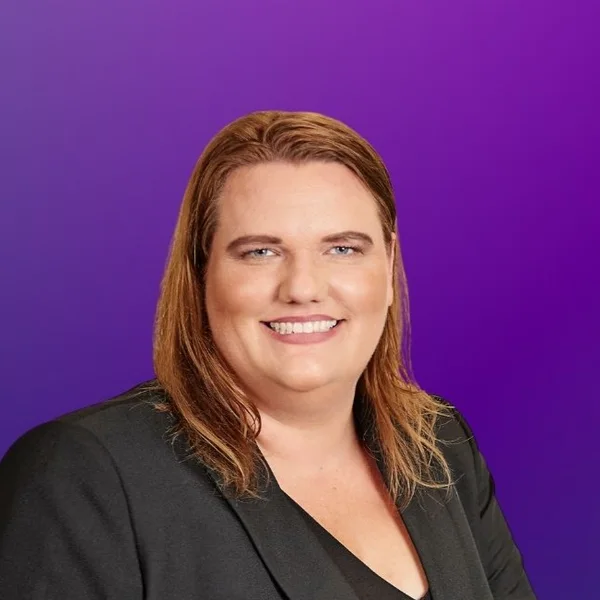
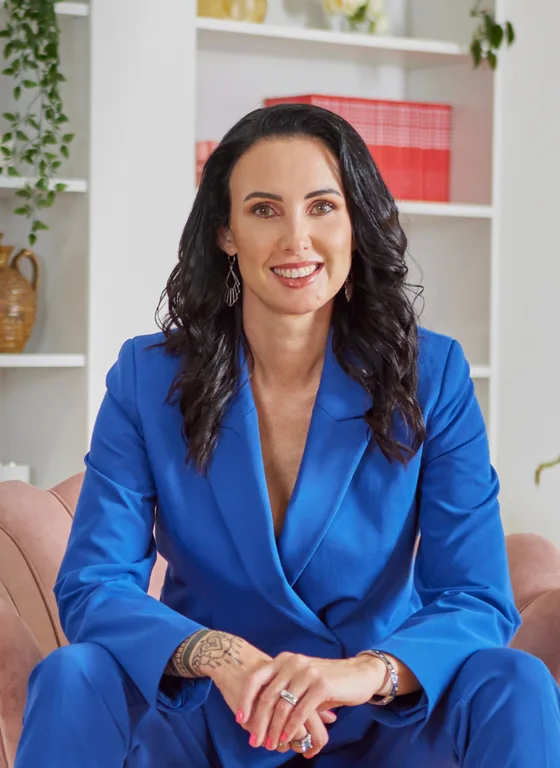
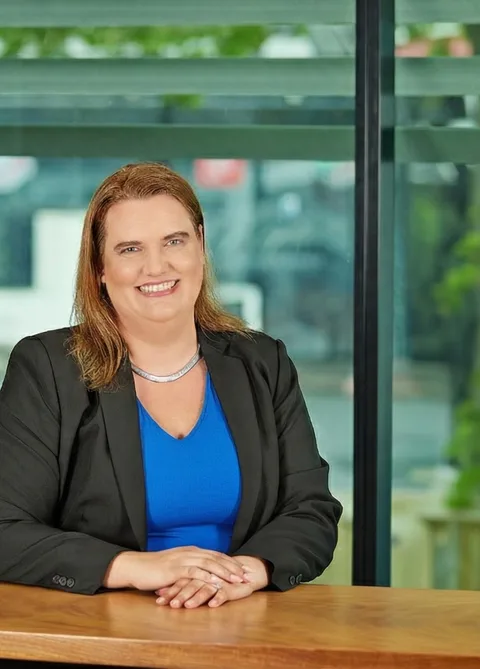
Sarah Cavanagh, owner and director
Sarah Owner & Director
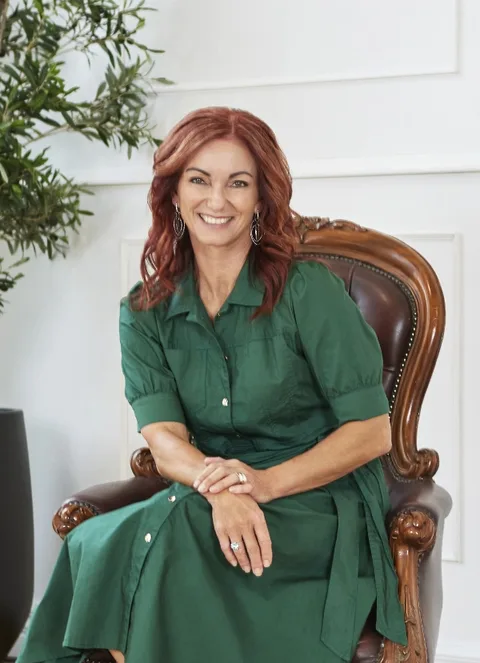
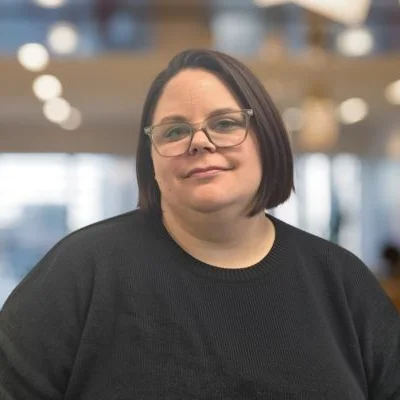
Carrie Thomas, general and commercial insurance adviser
Carrie General insurance

Led by 30+ years of experience

Free first consultation

46 providers compared

Everything you need, under one roof

Five areas of advice, one team. Scroll through them, or jump straight to what you need.

Smarter personal insurance

We strip away the jargon and give you personalised guidance, so your family, your income and your future are properly protected. We specialise in tailored cover for women and families, and for business owners too.

  • Life insuranceSupport for your whānau with funeral costs, debts and future needs.
  • Health insuranceSpecialists, tests and surgery, without waiting on a public list.
  • Trauma insuranceA lump sum for a critical illness or major injury, so you can focus on recovery.
  • Income protectionA portion of your income if illness or injury stops you working.
  • Mortgage repaymentYour mortgage paid through illness, disability or redundancy.
  • Total & permanent disablementA lump sum if you can never work again.
  • Key person & business coverKeeps a business going if a partner or key person is sick, injured or dies.
Smarter general & commercial insurance

Whether you are protecting your home, your lifestyle or your business, we compare insurers and tailor cover that fits, then stand beside you if you ever need to claim.

Home & lifestyle

  • Home & contents
  • Car, ute & SUV
  • Classic cars
  • Boat, motorbike & caravan
  • Landlord protection
  • Travel

Rural

  • Farms & lifestyle blocks
  • Machinery & livestock
  • Rural infrastructure

Business

  • Material damage
  • Business interruption
  • Commercial vehicles & fleets
  • Business travel

Liability

  • Public & statutory liability
  • Professional indemnity
  • Directors & officers
  • Cyber liability

Smarter mortgages

Paying off a mortgage quickly shouldn’t mean sacrificing your lifestyle. We are by your side through the whole property journey, not just the beginning, and available outside traditional hours when you need us.

  • New mortgagesYour first home, your next home, or an investment property.
  • Top-ups & extra lendingRenovations, debt consolidation or a major purchase, kept structured and sustainable.
  • RestructuringFlexibility for early repayments, cost certainty and a well-balanced spread of risk.
  • Bank comparisonsYour current offer checked against what other banks would give you for the same loan.

Smarter KiwiSaver & investments

Investing isn’t just for “finance people”. We help you choose the right strategy for your goals and values, whether that is a first home, long-term wealth or simply feeling more in control.

KiwiSaver

  • The right fund for your timeframe and risk comfort
  • Providers compared on performance, fees and values
  • Using KiwiSaver for your first home
  • Contributions that keep retirement on track

Investing

  • Managed funds & diversified portfolios
  • Ethical and sustainable options
  • Getting started with small amounts
  • Staying invested through ups and downs

Smarter financial coaching

Financial freedom starts with understanding your money. We focus on a conscious spending plan rather than a restrictive budget, with practical tools and non-judgemental guidance.

  • Spending plansTrack what comes in and goes out, and fund the life you want.
  • Debt consolidationTurn several high-interest debts into one manageable payment.
  • Personal loansStructured lending for a major purchase, refinanced safely.
  • Money mindsetDeal with the habits and worries that hold you back.

Kia ora, I’m Sarah.

My team and I have many decades of financial experience between us and would love to help you.

We share the same core values: a candid and straightforward approach and, most importantly, a shared passion for helping others. Whether it’s securing your dream home, making wise investments, or protecting your business or family, we are dedicated to assisting you. And if we can save you a significant amount of money along the way, that’s a win for everyone.

You always know where you stand with us. We offer genuine, honest advice, even if the truth hurts. We approach helping our clients just like we would our own family members.

Sarah CavanaghOwner & Director, The Smart Advice Collective

How we got here

  1. A team of two

    We started with mortgages and personal life and health insurance.

  2. Four advice lines

    We grew into fire and general insurance, commercial insurance, and KiwiSaver and investment advice.

  3. Eight advisers and a support team

    Every adviser is a woman. We’re really proud of that, and it’s on purpose.

  4. Emerging Business of the Year

    Recognised at the WealthPoint conference in Dunedin, August 2026.

“Women make fantastic financial advisors as we are natural problem solvers and bring an empathy and level of communication to the role that I think our clients really appreciate.” Sarah Cavanagh

Map of New Zealand showing adviser locations in Whangārei, Auckland, Rotorua, New Plymouth, Wellington and Christchurch.

A national team that’s local to you

Meet in person if you’re nearby, or work with any adviser online or by phone. Wherever you live in New Zealand, the right specialist is a call away.

9advisers
plus a support team
6cities
from Whangārei to Christchurch
46providers
banks, insurers and fund managers
30+years
Sarah’s experience in NZ advice
  • WhangāreiHollie
  • AucklandSarah, Rachael, Pal
  • RotoruaCarrie
  • New PlymouthDebra
  • WellingtonSakhi
  • ChristchurchJodi, Lorena

Meet the team

Advisers based from Whangārei to Christchurch, working with clients online, by phone or in person anywhere in New Zealand.

  • Sarah CavanaghAuckland

    Sarah Cavanagh

    Owner & Director. Personal insurance, KiwiSaver & investments

    Auckland & NZ-wide

    In New Zealand insurance and investment since 1996. Works with women, families and business owners.

  • Rachael ThompsonAuckland

    Rachael Thompson

    Mortgages, KiwiSaver & investments

    Auckland & NZ-wide

    A financial and mortgage adviser since 2013, and a property investor herself in Auckland and the regions.

  • Pal KaurAuckland

    Pal Kaur

    Property lending consultant

    Auckland & NZ-wide

    15+ years in banking and finance. Helps first-home buyers and investors, in English, Hindi or Punjabi.

  • Carrie ThomasRotorua

    Carrie Thomas

    Domestic, fire & general insurance. Commercial insurance

    Rotorua & NZ-wide

    15+ years in customer service, including work with the Earthquake Commission after the Kaikōura earthquake.

  • Hollie BaileyWhangārei

    Hollie Bailey

    Domestic & rural fire and general insurance

    Whangārei & NZ-wide

    A rural background and 13+ years in fire and general insurance. Home, contents, car and farm cover.

  • Debra SmaleNew Plymouth

    Debra Smale

    Domestic, fire & general insurance. Commercial insurance

    New Plymouth & NZ-wide

    8 years in general insurance. Quick and easy, without skipping the important details.

  • Jodi ImlachChristchurch

    Jodi Imlach

    Life & health insurance

    Christchurch & NZ-wide

    Helping families protect what they have built since 2020. A fierce advocate when a claim gets hard.

  • Lorena AvilaChristchurch

    Lorena Avila

    Personal insurance

    Christchurch & NZ-wide

    Life, health and business insurance for individuals, families and businesses, explained simply and honestly.

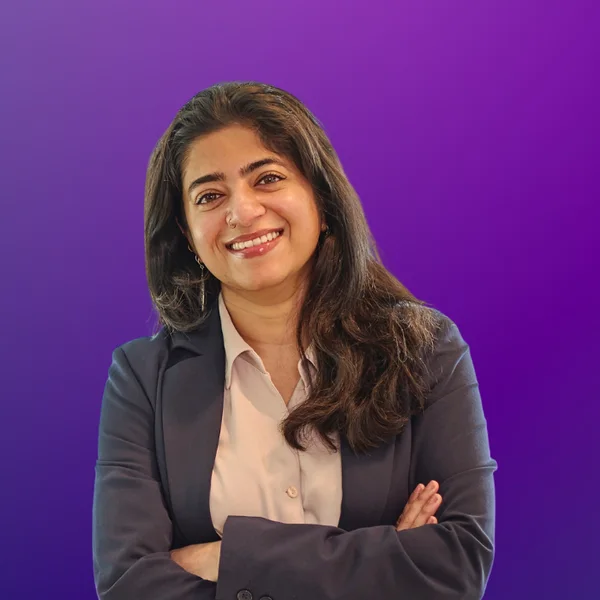
  • Sakhi NairWellington

    Sakhi Nair

    KiwiSaver, investments & personal insurance

    Wellington & NZ-wide

    A former patisserie chef who brings hospitality’s people-first service to financial advice.

Amy Morris

Amy Morris, Administration Manager

The calm in the middle of the storm. Amy keeps everything organised behind the scenes so every step feels simple for you.

Build your advice business with us

Experienced insurance or mortgage adviser, or a finance professional ready for the next step? Join a forward-thinking collective that puts your independence and success first.

  • Work from home with flexible hours
  • Generous commission splits
  • Build and own your client base
  • Coaching and mentoring from principals with 45+ years’ combined experience

In our clients’ words

Nothing felt too hard. We always felt supported.

I honestly can’t recommend Sarah Cavanagh and The Smart Advice Collective enough. From the moment Sarah took over our case, everything moved quickly, smoothly, and professionally. Her communication has been absolutely amazing, always keeping us updated, following through on everything she said she would do, and making what felt like a stressful situation so much easier to navigate.

Sam DunnAbout Sarah Cavanagh

An insurance adviser who has integrity.

Sarah is focused on her client 100%. Everything she does is aligned to making a real difference to her client. … She has a way of educating her clients throughout the process so that they truly understand what insurance they have and what it will do for them when they need it.

Gillian Winita-HeadleyAbout Sarah Cavanagh

Arranged a very good deal.

I was a little sceptical about mortgage brokers in the past, but Rachael … arranged a very good deal for me. I am very happy and thankful for her support during difficult personal circumstances and I will certainly use her services for my future property investments.

KrzysAbout Rachael Thompson

Jodi is an emotional support kitty for her clients and a ferocious tiger for getting results.

For four months, I don’t think she gave that insurance company a moment’s peace. She challenged the decision, pushed for answers, and kept fighting for them to honour what was clearly outlined in the terms of my policy. … And she succeeded. My surgery is now fully covered …

A client of Jodi’sAbout Jodi Imlach

When the right cover counted

Real claims our advisers have helped with. Names are kept private, the outcomes are not.

$593,000+paid out across just four of these claims
  • Aggressive breast cancer, trauma cover$250,000+
  • Melanoma on the shoulder, trauma cover$180,000+
  • Melanoma found during a review, trauma cover$150,000
  • Broken ankle, injury cover$13,000

Swipe or use the arrows to read each story

  • Trauma

    $150,000

    A routine review changed her life

    A new client in her late 50s mentioned a mole removed in her lunch break. It was melanoma. Her trauma cover paid out in full, so she cleared her mortgage and cut back to three days a week to look after her grandkids.

  • Injury

    $13,000

    Money they didn’t know they were owed

    During a review, a client mentioned breaking her ankle 18 months earlier. Her injury cover qualified, and the payment arrived just before Christmas.

  • Trauma & mortgage repayment

    $250,000+

    She kept her home through cancer treatment

    A year after buying her house, a client was diagnosed with aggressive breast cancer. Trauma cover paid for chemotherapy not funded by Pharmac, then mortgage repayment cover kept her mortgage paid while she recovered from surgery.

  • Trauma & health

    $180,000+

    Back at work the next day

    A landscape gardener had a large melanoma removed from his shoulder. Health insurance covered the specialist removal, and his trauma cover paid out in full.

  • Health

    Overseas

    Treatment that wasn’t available here

    A client diagnosed with a benign brain tumour needed treatment only available in Australia. Her health insurance covered it overseas, and her trauma claim was paid as well.

  • Health

    4 months

    An adviser who would not give up

    When an insurer declined a solo mum’s carpal tunnel surgery, Jodi challenged the decision for four months until it was covered in full.

  • Health

    Fast-tracked

    No waiting list for a 4-year-old

    After a rough-and-tumble game gave a little girl a hernia, health insurance meant a quick referral to a paediatric surgeon and surgery at Starship.

  • Vehicle

    24 hours

    Approved, repaired and back on the road

    A high-value vehicle needed a specialist windscreen. The adviser coordinated insurer and dealership, and the claim was approved and fixed within a day.

Read the full claim stories(opens in a new tab)

How we work with you

Simple, direct and stress-free, from the first hello to years down the track.

  1. Get in touch

    Call, email or use our form. We work online, by phone or in person, anywhere in New Zealand.

  2. A free first chat

    We get to know your goals and situation and see if we’re the right fit. No cost, no obligation.

  3. Clear options

    We compare providers and walk you through the benefits, costs and trade-offs before you commit.

  4. We do the legwork

    Applications, paperwork, transfers and chasing the bank or insurer. All handled for you.

  5. Here for the long run

    Annual reviews, help with claims, and support whenever questions pop up.

What does advice cost?

Often, nothing directly.

Not having a plan can cost far more in the long run. Here is exactly how we are paid, so you always know where you stand.

We never hold your money or insure you ourselves. Your investments and policies stay in your name, with regulated New Zealand providers.

Your first conversation
FreeNo obligation to continue.
Insurance & mortgage advice
No direct costWe’re paid by the insurer or lender.
KiwiSaver review or switch
FreeWe handle the transfer for you.
Investment advice
A transparent feeA percentage, disclosed upfront and tax-deductible.
Coaching & non-standard loans
Agreed upfrontAny fee is discussed before we start.
How advisers like us are paid
YouGet advice and ongoing support
Your adviserCompares, recommends and sets it up
Bank or insurerPays your adviser when your loan or policy starts

You pay your premiums or loan repayments to the provider, as usual.

Backing New Zealand businesses

Premises, vehicles, people and cyber risk. We take the hassle out of commercial cover so you can focus on running your business with confidence.

  • Property & interruption Material damage and business interruption cover for premises, equipment and stock.
  • Liability Public, statutory, professional indemnity and directors & officers.
  • Cyber Hacking, data breaches and online fraud, including recovery and legal costs.
  • Key people Key person and business partner cover, so the business carries on if someone can’t.

Try the numbers yourself

Three free tools to help you see where you stand. Have a play, then talk it through with one of our advisers.

Your two-minute money check-up

Six quick questions about the things that matter most when life doesn’t go to plan. You’ll get a score and a short list of where to start.

  • Nothing is sent or saved
  • Plain English, no jargon
  • Matched to the right adviser

Question 1 of 6

If you couldn’t work for six months, could you still pay the bills?

ACC covers accidents, but not illness, and illness is a common reason people stop earning.

If something happened to you, could your family clear the mortgage and other debts?

Life and trauma cover give the people who rely on you money and time to adjust.

Has your home or contents sum insured been checked in the last two years?

Your sum insured is the most an insurer will pay. Rebuild costs change, and it is easy to fall behind.

Do you know which KiwiSaver fund you’re in, and why it suits you?

Fund type and fees make a big difference to your balance by 65.

Has your mortgage been reviewed in the last 12 months?

Loan structure, fixed terms and small extra repayments can add up to thousands.

Do you have three months of essential costs set aside for emergencies?

A buffer stops a surprise bill turning into debt.

Thinking about a mortgage?

Estimate your repayments in seconds, see what a little extra each payment could save, then talk to Rachael or Pal about what’s realistic for you.

$650,000
5.00%
30 years
Repayments

Weekly repayment

$805

Amount borrowed
$650,000
Total interest
$605,296
Total repaid
$1,255,296
Talk to a mortgage adviser

What if you paid a little extra?

$50

4 yrs 1 mthsooner mortgage-free

$93,780less interest

Loan balance over timeStandardWith extra

An estimate for a principal and interest loan at one rate for the whole term. Real rates change over time, lenders calculate slightly differently and some fixed-rate loans limit extra repayments. This is general information, not financial advice.

What could your KiwiSaver be worth at 65?

A rough projection in today’s dollars, using the same assumptions KiwiSaver providers must use on your annual statement.

30
$70,000
$20,000
You contribute
Fund type

At 65 you could have about

$0

in today’s dollars, or about $0 a week from 65 to 90

Balance today
$0
You put in
$0
Your employer adds
$0
The Government adds
$0
Investment returns
$0
Get a free KiwiSaver review

A rough illustration using the Government’s projection assumptions, not a guarantee or financial advice. Returns go up and down.

How your balance buildsMoney paid inInvestment returns

Same savings, different fund

Tap a fund to try it.

How this is worked out

We use the assumptions the Government sets for KiwiSaver projections: yearly returns after fees and tax of 2.5% (conservative), 3.5% (balanced), 4.5% (growth) and 5.5% (aggressive), wages rising 3.5% a year and inflation of 2% a year, with results shown in today’s dollars.

It assumes you stay employed and in the same fund until 65, your employer contributes 3.5% of your pay (less employer superannuation contribution tax), you receive the government contribution of up to $260.72 each year your income is $180,000 or less, and you make no withdrawals. The weekly figure assumes your balance keeps earning 2.5% a year after 65 and is spent evenly until 90.

It doesn’t include future changes to contribution rates or rules. This is a rough illustration, not financial advice.Read the FMA’s projection assumptions (opens in a new tab)

Money guides, in plain English

Quick, visual answers to the questions our advisers hear most. Pick a topic to explore.

Which KiwiSaver fund suits you?

It mostly comes down to when you’ll need the money, and how you feel about ups and downs.

  • ConservativeLower risk and a steadier balance. Suits you if you’ll use your savings soon, such as for a first home or retirement.
  • BalancedA mix of income and growth assets, aiming for moderate to high returns with fewer big swings.
  • GrowthBigger ups and downs, with more potential to grow. Suits you if you won’t touch the money for many years.

Free money from the Government

Contribute at least $1,042.86 between 1 July and 30 June and the Government adds 25 cents per dollar.

Not available if your income is over $180,000. Since 1 April 2026, the default contribution for employees and employers is 3.5% of pay.

When can you withdraw?

  • At 65
  • Your first home
  • Serious illness
  • Significant hardship
  • Moving overseas permanently (with restrictions)

For a first home you can usually take out most of your balance, leaving at least $1,000.

Small fees, big difference

Even a 0.5% difference in fees compounds over decades. Reviewing or switching your KiwiSaver with us is free, and a switch usually takes 10 to 20 business days.

Review my KiwiSaver

Natural disaster cover comes in two layers

Know where one stops and the other starts, so there are no gaps when you need it.

Layer 2Your private insurerDamage above the NHC cap, plus storms, floods, fire, theft and accidental damage, depending on your policy.
Layer 1Natural Hazards Commission (formerly EQC)The first $300,000 + GST of damage to your home from earthquakes, landslips, volcanic activity and tsunami.

NHC cover comes automatically when your home insurance includes fire cover.

Excess vs premium

Move the slider. A higher excess usually means a lower premium.

Illustration only. Your real numbers depend on your insurer and your home.

Replacement or indemnity?

ReplacementReplaces items with new equivalents. Stronger protection and the most common choice.
IndemnityPays today’s value, after depreciation.

Your home’s sum insured should match the full rebuild cost, not its market value.

Which cover does what?

Some covers pay a lump sum, some replace income every month, and health insurance pays for treatment.

CoverWhat it protectsHow it pays
Life insuranceYour whānau, if you pass awayLump sum
TraumaYou, through a serious illness or injuryLump sum
Total & permanent disablementYou, if you can never work againLump sum
Income protectionYour income, if you can’t workMonthly
Mortgage repaymentYour home loan, if you can’t workMonthly
Health insuranceYour treatment, without the waiting listMedical costs

Ways insurance can protect you

  • Keep the family homeIncome and mortgage cover mean a short-term illness doesn’t force a sale.
  • Choose your treatmentFunds to pursue the medical options that fit your beliefs and values.
  • Time with loved onesMoney so family can take time off work to care for you.
  • Treatment on your scheduleNot at the mercy of long hospital waiting lists.
  • Protect your childrenCover for their medical care when it matters most.
  • Keep plans on trackYour family’s plans continue, whatever happens.

The three questions everyone asks

How much can I borrow?Depends on your income, debts and expenses.
How much will it cost?Depends on the amount, your deposit and interest rates at the time.
How long will it take?Lenders usually take one to two weeks to assess an application.

The deposit most banks look for

Investment property30%
Home to live in20%
First Home Loan5%

For existing properties. New builds are exempt from the Reserve Bank’s deposit rules. The First Home Loan is through Kāinga Ora and participating lenders, with income and price caps.

Ways to structure your loan

  • FixedCertainty of cost for a set term.
  • FloatingFlexibility to make extra repayments.
  • SplitA spread of risk across both.
Estimate your repayments

Going it alone vs working with an adviser

TopicOn your ownWith The Smart Advice Collective
Comparing providersYou research each one yourselfWe compare many banks and insurers for you
Getting the amount rightEasy to guess and end up underinsuredWe check rebuild costs and cover levels
The fine printExclusions are yours to findWe explain what is and isn’t covered
Making a claimYou deal with the provider aloneWe guide and advocate for you
As life changesUp to you to rememberAnnual reviews keep it up to date
What it costsYour timeOften no direct cost to you

The Smart Girls Club

A community of women in New Zealand sharing knowledge, experience and support, so we can all take charge of our financial future.

  • The Smart Girls Club Podcast

    Sarah hosts open, honest conversations about everything from insurance and financial planning to wellness. Yes, even money.

  • Events, workshops and the Book Club

    Monthly book discussions and networking for ambitious women in Auckland. The Book Club is taking a break, so follow along to hear when it’s back.

  • Speaking at your event

    We speak at finance events, women’s education evenings and businesses about managing insurance and money in a smarter, savvier way.

We compare, so you don’t have to

We’re independent advisers, not tied to one bank or insurer. We work with 46 New Zealand providers to find the right fit for you.

Banks & lenders

  • ANZ
  • ASB
  • BNZ
  • Westpac
  • Kiwibank
  • Co-operative Bank
  • SBS
  • Unity
  • Avanti Finance
  • Pepper Money
  • First Mortgage Trust
  • Finbase
  • Bizcap
  • Prospa

Life & health insurers

  • AIA
  • Asteron Life
  • Fidelity Life
  • Partners Life
  • Resolution Life
  • nib
  • Southern Cross
  • Accuro
  • PPS Mutual

General & commercial insurers

  • Vero
  • NZI
  • QBE
  • Zurich
  • Chubb
  • AMP
  • Lumley
  • Delta Insurance
  • Dual
  • Emergence
  • Ando
  • 360
  • Classic Cover
  • Star Insurance Specialists
  • Southern Cross Travel Insurance

KiwiSaver & investments

  • Booster
  • Generate
  • Fisher Funds
  • Milford
  • NZ Funds
  • Pathfinder
  • Always Ethical
  • Goals Getter

A trusted network beyond money

Lawyers, accountants, architects, HR specialists and health professionals. After decades in finance, we can introduce you to more than 40 people we personally recommend.

See our recommended professionals(opens in a new tab)

Straight answers

We believe in growing your financial knowledge as well as your wealth. Can’t see your question? We’re always happy to talk it through.

Ask us anythingMore FAQs and a glossary of finance terms(opens in a new tab)

Working with us

Is the first consultation really free?

Yes. Your first chat is completely free, and often the whole process is fee-free to you. It is simply a chance to understand your needs and see whether we are the right fit.

Do I need to live in Auckland?

No. Our advisers are based in Auckland, Whangārei, Rotorua, New Plymouth, Wellington and Christchurch, and we work with clients all over New Zealand online, over the phone or in person.

Do you hold my money or insure me?

No. We act as brokers and advisers. Your investments and insurance stay in your name, with reputable, regulated providers we choose together.

How often will I hear from you?

Insurance and mortgage clients get an annual renewal review, help with claims and support whenever questions pop up. Investment clients get quarterly or annual updates, an annual review meeting and extra check-ins whenever needed.

Is there a minimum investment?

No. We look at your whole financial picture, not just the size of your investments. Many people without large assets benefit hugely from a plan, and if we are not the right fit we will point you to someone who is.

Insurance

What does sum insured mean for my home?

It is the most your insurer will pay if your home is destroyed. It should reflect the full rebuild cost, not the market value, and be reviewed regularly, especially after renovations.

Replacement or indemnity cover?

Replacement cover replaces items with new equivalents. Indemnity cover pays the current value after depreciation. Replacement offers stronger protection and is the most common choice for Kiwi households.

Does my home insurance cover flatmates or Airbnb guests?

Usually not automatically. Flatmates need their own contents cover, and you must tell your insurer if you rent your home out, even occasionally. We can check your policy wording so there are no surprises at claim time.

Can you help me make a claim?

Yes. We guide you through the process and advocate on your behalf, especially when things feel stressful. Our claim stories show what that looks like.

Mortgages & KiwiSaver

How much can I borrow, and how long does it take?

It depends on your income, debts and expenses, and the cost depends on your deposit and interest rates at the time. Lenders usually take one to two weeks to assess an application.

What do I need for a mortgage approval?

Details of your income, existing debt and fixed expenses, with documents to support them, plus proof of your deposit and any help from family.

Can I use KiwiSaver to buy my first home?

Yes. You can usually withdraw most of your balance, leaving at least $1,000, to buy your first home or land to build on.

Does it cost anything to switch KiwiSaver providers?

No. Reviewing or switching is free, and it usually takes 10 to 20 business days. We handle the whole transfer, and you don’t need to tell your old provider.

Ready to get started?

Book a free consultation. Tell us what you need and we’ll show you who to talk to, or use our enquiry form and we’ll come to you.

What can we help you with?

Your advice, protected

Who gives the advice, what to do if something isn’t right, and how your information is looked after.

Who gives the advice

Our advisers provide financial advice on behalf of Wealthpoint Limited (FSP678011), which holds a Financial Advice Provider licence.

Each adviser’s disclosure statement explains what they advise on, how they are paid and any conflicts of interest. It’s free: ask your adviser for a copy, or find it on their profile.

Check the Financial Service Providers Register(opens in a new tab)

If something isn’t right

  1. Tell your adviserCall or email and explain what has gone wrong and what you would like to happen.
  2. Wealthpoint’s complaints processIf it isn’t resolved, Wealthpoint Limited manages complaints about its advisers. Contact details to confirm
  3. An independent dispute resolution schemeStill not sorted? You can take it to an independent scheme. It costs you nothing. Scheme name to confirm

Your privacy

Your details are held securely by your adviser’s business and Wealthpoint Limited, and used to give you advice and look after your products. You can ask to see or correct the information held about you at any time.

Read the privacy policy (opens in a new tab)

To confirm before launch: the name and contact details of Wealthpoint’s dispute resolution scheme; how clients reach Wealthpoint’s complaints team. SAC’s current adviser disclosure statements don’t include a complaints process or dispute scheme, which the disclosure rules call for.

Get startedEmail us